



01
Days, not months.
Sign up online, set up your page, start onboarding members.
Core banking · eKYC · Lending · Reporting
OpenFinance.PH gives your institution a complete digital upgrade: self-onboarding, reusable eKYC, AI-assisted lending, electronic post-dated payments and regulatory reports, on one platform you can sign up for today. Your brand stays. Your members stay. The cost is shared.
Built by Traxion Tech, serving institutions across Luzon, the Visayas and Mindanao since 2015.
Example RBPay member app home screen, showing the wallet balance, recent transactions and a news card.
Example DigiCOOP member app home screen, showing the wallet balance, recent transactions and a news card.
Example MicroPay member app home screen, showing the wallet balance, recent transactions and a news card.
Built for
Why OpenFinance.PH
You know your members better than any app ever will. You know their farms, their stores, their families. But when they need to pay a bill, send money home or check a balance at 10pm, they open someone else's app.
Building your own digital banking used to mean a seven-figure project, a vendor you can't leave and a year of waiting. OpenFinance.PH changes the math: one platform, built once, shared by many, so each institution pays only for what it uses.
My e-PDCs
Agri Loan · No. 0012-4581
PHP29,150.00
Outstanding balance
1 of 12 e-PDCs collected
Next: Oct 30
Schedule
Monthly · 12 instruments
e-PDC No. 0001
Auto-debit · Savings
PHP 2,850.00
Collectede-PDC No. 0002
Auto-debit · Savings
PHP 2,850.00
Next duee-PDC No. 0003
Auto-debit · Savings
PHP 2,850.00
Schedulede-PDC No. 0004
Auto-debit · Savings
PHP 2,850.00
Schedulede-PDC No. 0005
Auto-debit · Savings
PHP 2,850.00
ScheduledEach e-PDC is collected automatically from your savings account on its due date. No more trips to the branch.
Add an e-PDC
My e-PDCs
Productive Loan · No. 0034-1102
PHP29,150.00
Outstanding balance
1 of 12 e-PDCs collected
Next: Oct 30
Schedule
Monthly · 12 instruments
e-PDC No. 0001
Auto-debit · Savings
PHP 2,850.00
Collectede-PDC No. 0002
Auto-debit · Savings
PHP 2,850.00
Next duee-PDC No. 0003
Auto-debit · Savings
PHP 2,850.00
Schedulede-PDC No. 0004
Auto-debit · Savings
PHP 2,850.00
Schedulede-PDC No. 0005
Auto-debit · Savings
PHP 2,850.00
ScheduledEach e-PDC is collected automatically from your savings account on its due date. No more trips to the branch.
Add an e-PDC
My e-PDCs
Group Loan · Center 3
PHP14,950.00
Outstanding balance
1 of 24 e-PDCs collected
Next: Oct 14
Schedule
Weekly · 24 instruments
e-PDC No. 0001
Auto-debit · Savings
PHP 650.00
Collectede-PDC No. 0002
Auto-debit · Savings
PHP 650.00
Next duee-PDC No. 0003
Auto-debit · Savings
PHP 650.00
Schedulede-PDC No. 0004
Auto-debit · Savings
PHP 650.00
Schedulede-PDC No. 0005
Auto-debit · Savings
PHP 650.00
ScheduledEach e-PDC is collected automatically from your savings account on its due date. No more trips to the branch.
Add an e-PDC
Sign up online, set up your page, start onboarding members.
Your borrowers get a post-dated payment instrument without a current account.
Members verify their identity once and share it with your institution, with their consent.
Behind every account, a person
You've spent years earning your community's trust. The right technology should help you be there for them, wherever life takes them.
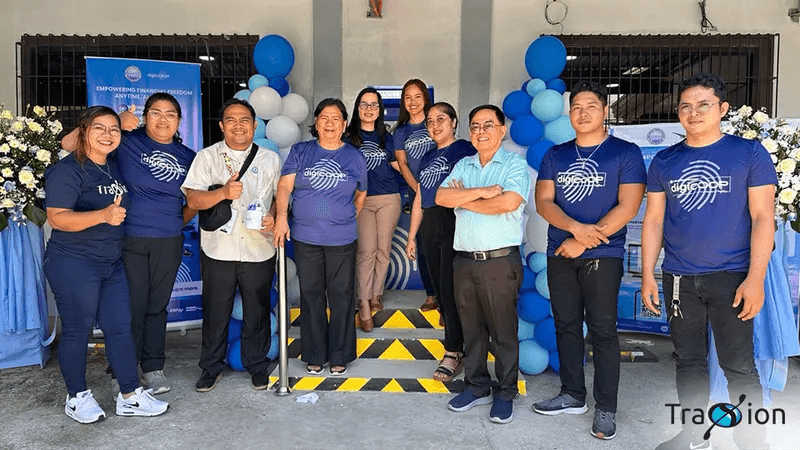
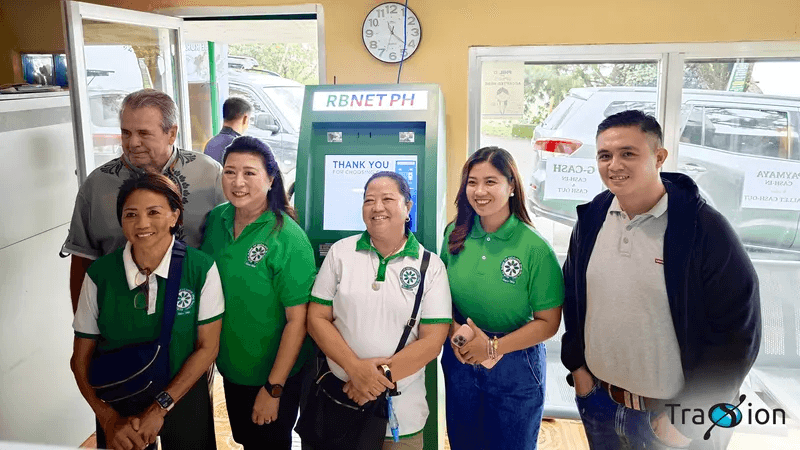
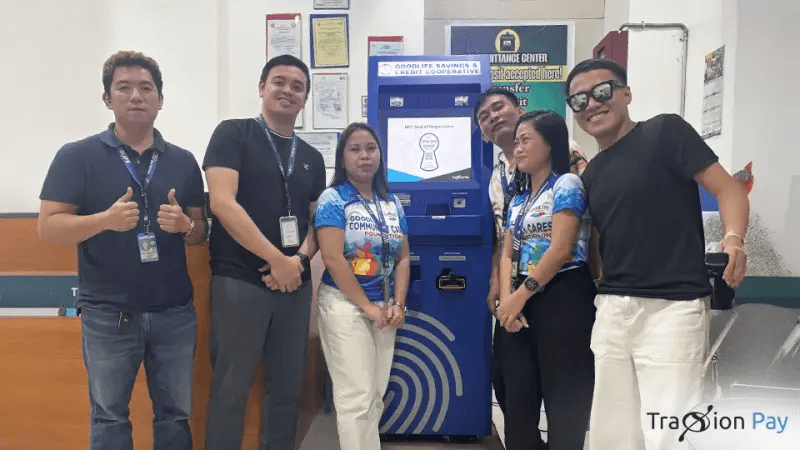
Existing TraxionPay, DigiCOOP and RBPay deployments. These stories describe the work behind our platform. Meet the COOPNET community ↗ (opens in a new tab)
Cabadbaran City, Agusan del Norte
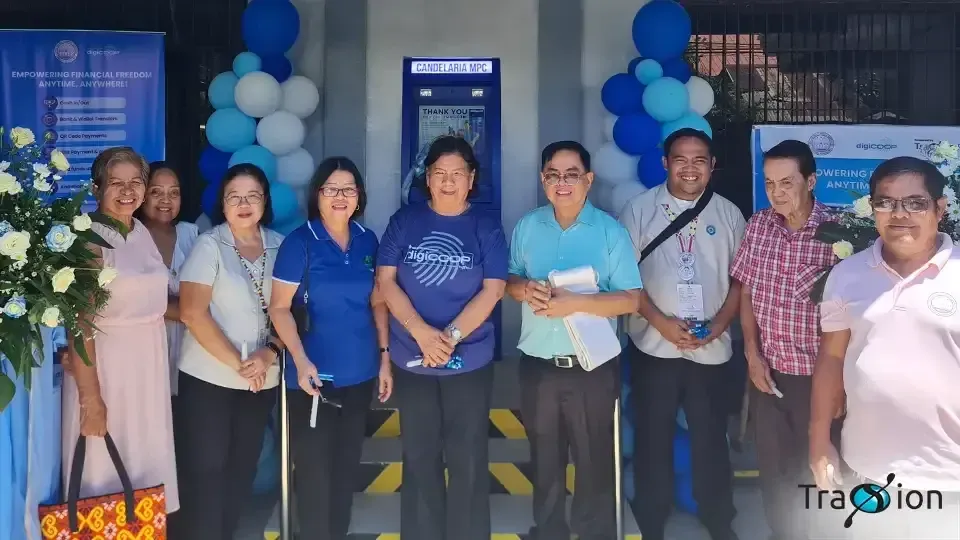
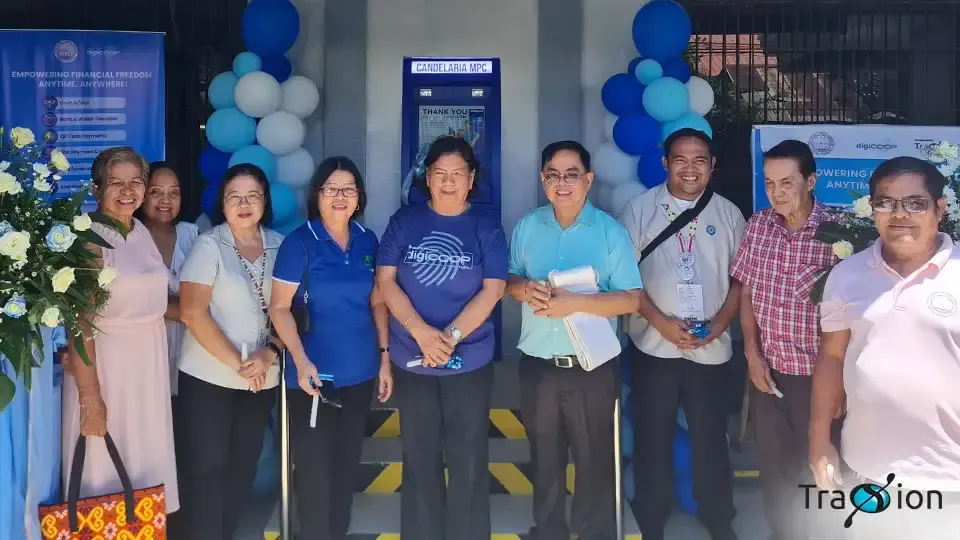
DigiCOOP and Candelaria MPC brought CARAGA's first Cash Teller Machine to their community.
Read the story about Candelaria MPC (opens in a new tab)Negros Occidental
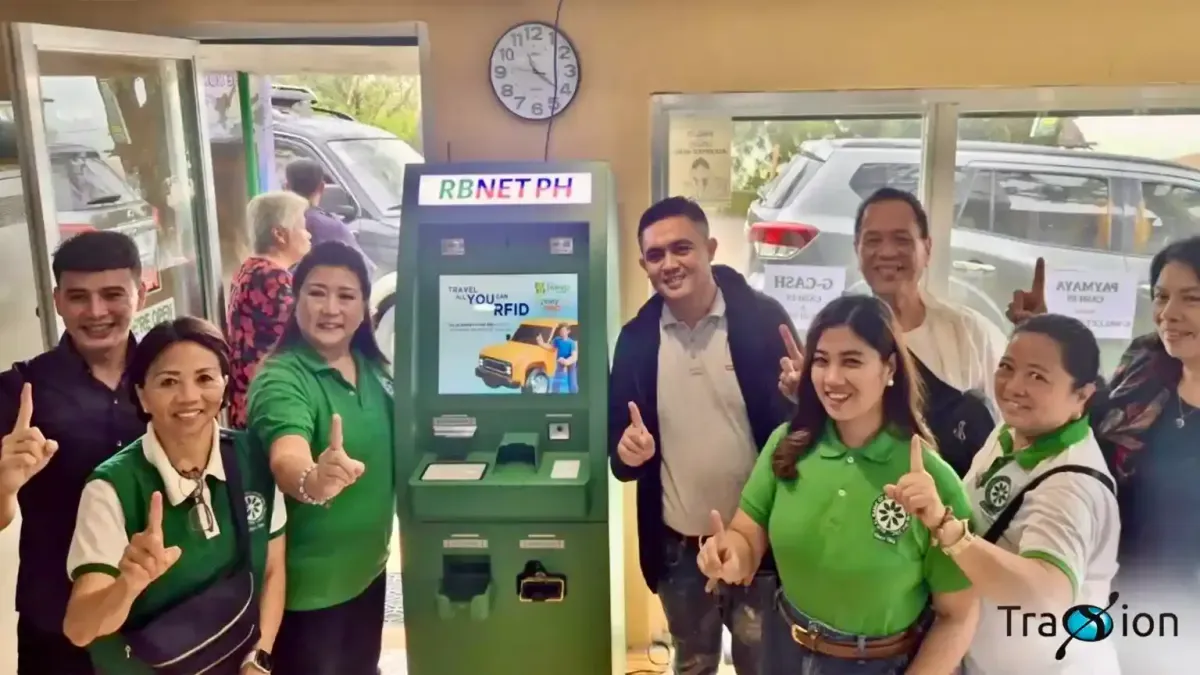
RBPay's Cash Teller Machine reached the bank's Don Salvador Benedicto branch, so members no longer make the long trip to bank.
Read the story about Rural Bank of Escalante (opens in a new tab)Digos City, Davao del Sur
Two TraxionPay-powered Cash Teller Machines brought financial access closer to members.
Read the story about Goodlife Savings Credit Cooperative (opens in a new tab)Existing TraxionPay, DigiCOOP and RBPay deployments. These stories describe the work behind our platform. Meet the COOPNET community ↗ (opens in a new tab)
How it works
Day 1 to month-end, on one platform. Your page is live the same day you sign up.
Sign up your institutionDay 1 · Set up
Sign up and e-sign online. Your page is live the same day.
Sandbox tests for your core banking system, or file exchange if it has no API.
Every day · Serve members
Reuse verified identities through eKYC.ph, with the member's consent.
AI scores and explains each application. Your officer approves.
e-PDCs created from the repayment schedule, collected on each due date.
Month-end · Report
BSP, CIC and CDA reports ready for one-click sign-off.
White-label
Members never see our name. They see yours: your colours, your products, and your institution's reputation, on technology that used to be reserved for the biggest banks.
Register your institution, reserve your page and e-sign the agreement. Free.
Upload your logo, choose your colors, import your members, and connect your core in the sandbox when you're ready.
Share your link. Members activate, verify through eKYC.ph and start banking with you on their phones.



Hi, Juancho!
Mobile: 09359245649


RBPay Wallet

2452 1123 5798 1234


Available Balance:


Cash
In

Send
Money

More
Recent Transactions

Send Money
Mar 26, 2026, 04:32 PM
-PHP 5,000.00
Pay Bills
Mar 26, 2026, 04:32 PM
-PHP 400.30
Add Funds
Mar 26, 2026, 04:32 PM
+PHP 40,000.00
News and Updates
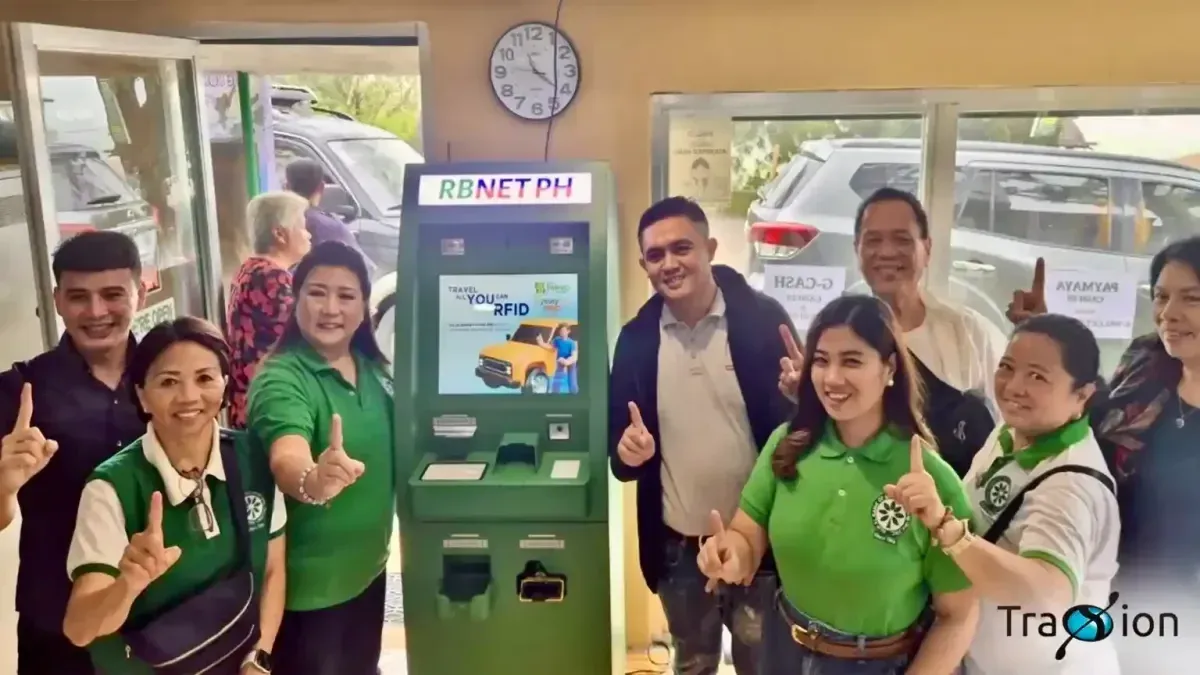
RBPay’s Cash Teller Machine (CTM) launched in Rural Bank of Escalante, Inc.’s (RBEI) Don Salvador Benedicto Branch Lite Unit (DSB-BLU) branch in Negros Occidental during their 1st anniversary on October 21, 2024.
Many institutions. One complete platform.
RBPay for rural banks. DigiCOOP for cooperatives. MicroPay for MFIs. They come together in OpenFinance.PH, from a member's first hello to your month-end report.
One platform. End to end.
Your brand, data and decisions stay yours.
Members download one app and see it in your institution's colors and terms.
Spotlight · e-PDC
Most of your borrowers will never open a checking account. So the collection discipline big lenders take for granted has never been available to you. e-PDC fixes that.
Release the loan.The platform reads the repayment schedule and creates one e-PDC for every due date.
Your borrower confirms.They see every instrument in the app and choose where each one pulls from: savings, wallet, or both.
It collects on the date.The payment moves automatically. You see it posted. They get a receipt.
A paper post-dated check becomes an e-PDC. When the loan is released, the platform creates twelve monthly e-PDCs of ₱2,850.00; the borrower chooses to pull them from savings and wallet, and the first one is collected on its due date.
Collected on the date. You see it posted; they get a receipt.
| Paper post-dated checks | e-PDC | |
|---|---|---|
| Checking account needed | Yes, with a ₱5,000 to ₱10,000 maintaining balance | No |
| Cost to the borrower | Checkbook plus bounced check penalties of ₱2,000 and up | Nothing |
| Cost to the lender | Handling, storage, deposit runs | ₱3 per successful collection (against ₱6 per check leaf) |
| Lost or altered checks | It happens | Digital records, with changes traceable on blockchain |
| Proof in a dispute | The paper trail you hope you kept | Tamper-evident record of issuance, consent and execution |
Paper: Yes, with a ₱5,000 to ₱10,000 maintaining balance
e-PDC: No
Paper: Checkbook plus bounced check penalties of ₱2,000 and up
e-PDC: Nothing
Paper: Handling, storage, deposit runs
e-PDC: ₱3 per successful collection (against ₱6 per check leaf)
Paper: It happens
e-PDC: Digital records, with changes traceable on blockchain
Paper: The paper trail you hope you kept
e-PDC: Tamper-evident record of issuance, consent and execution
Illustration: a ₱5,000 to ₱10,000 maintaining balance per checking account, and ₱3 per successful e-PDC collection, one a month per borrower.
Members can issue e-PDCs to suppliers, landlords or anyone with a bank account or e-wallet.
Runs on Direct Debit PH, so it works alongside the banking system you already use.
e-PDC is a patent-pending Traxion technology.
Spotlight · eKYC.ph
Every time a member joins a new institution, they upload the same ID, take the same selfie, and someone pays for the same check. eKYC.ph ends that.
Lower onboarding cost. Reusing a verified identity costs a fraction of a fresh eKYC.
Faster account opening. Members who are already verified can be onboarded in minutes.
Less data to guard. Verify without storing copies of everyone's IDs.
You still decide. Each institution keeps its own due diligence decision and risk rating.
Your institution stays yours
The first question every board asks: if we share a platform with other banks and coops, will they see our members? The answer is no, and we put it in writing.
Members see your name, logo and colors. Your credit policy, records and relationships stay with you.
Not other banks, not other coops, not Traxion's affiliates. Every institution is an ordinary tenant with the same walls.
A member can choose to see balances from several institutions in one app. Institutions never see each other's accounts.
We don't market to your members, and that commitment survives even if you leave.
Give 60 days' notice and receive a full export of your data.
Compliance and trust
Traxion Pay Inc. is a BSP-licensed Electronic Money Issuer and a BSP-registered Operator of a Payment System.
Pricing
₱0
₱5,000to ₱35,000 a month, by member count
₱3 per successful collection (against ₱6 per check leaf), paid by the lender. Free for borrowers.
Priced per verification, at a fraction of a fresh eKYC.
API or on-site connector quoted to your setup. File-based connection is free.
₱3,000
a month, paid by your institution · free for borrowers
Institutions with fewer than 1,000 members start at ₱5,000 a month. Prices exclude VAT.
No. We connect to the core you already have, through its API, a secure on-site connector, or file exchange if it has no API at all.
No. Every institution is walled off from every other. Only the member can choose to view their own accounts across institutions, and no institution ever sees another's balances or transactions.
You do. Deposits, loans, credit decisions and member records stay with your institution.
It's an electronic payment instruction that works the way post-dated checks are used today: issued in advance, held by the payee and executed on its date. It doesn't need a checking account.
Your institution sets the rules at onboarding, including whether to retry and how you're notified. Every attempt is recorded.
No. It gives your credit officer a score, the reasons behind it and a recommendation. A person at your institution makes the final decision.
No. Personal data stays off-chain. The blockchain keeps tamper-evident proof that a verification, consent or payment instruction happened.
OpenFinance.PH is a private platform by Traxion and is not operated or endorsed by the BSP. We share the goal of the BSP's open finance agenda: consent-based data sharing that gives Filipinos more control over their financial lives. Our focus is making that possible for smaller institutions.
Your page and account opening can be ready the day you sign up. Connecting your core depends on your setup, and the sandbox lets your team move at its own pace.
Yes. Give 60 days' notice and you receive a full export of your data.
Get started
Sign up today and have your institution's page live this afternoon. No vendor project, no upfront cost, no lock-in.